Economic Research Forum (ERF)

Who can work from home in MENA?

1699
Which jobs can be done from home, who does them and how prevalent are they in different countries? This column reports evidence on working from home in over 50 countries, including Egypt, Jordan and Tunisia.

In a nutshell

Why certain regions or types of workers have jobs less amenable to working from home is a key issue for the design of public policies.

There would be substantial benefits from improving access to digital technologies in MENA, both in normal times and during the pandemic.

But since the adoption of new technologies does not happen overnight – especially when the baseline level is very low as in the MENA region – a broader response stimulating the economy and supporting those who cannot find a job is key.

With the spread of Covid-19 and the implementation of social distancing measures, identifying who can work from home has become a critical question.

In a new article, we estimate who has the jobs more amenable to working from home in 53 countries, including three from the Middle East and North Africa (MENA).

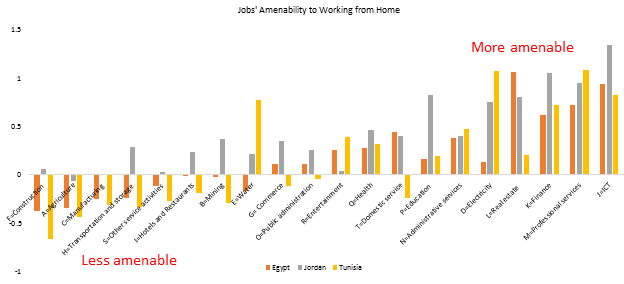
Out of those three, we find that Jordan ranks best in terms of its jobs’ amenability to working from home, Egypt is at middle and Tunisia at the bottom. This is not surprising given that Jordan has a much higher rate of internet penetration, a factor that is critical to working from home.

But there are dramatic differences within countries as well. Less educated, older and informal workers are substantially less likely to have jobs amenable to working from home in each of the three countries.

This is driven by less educated and informal workers having jobs more intensive in physical tasks that cannot be done at home, and by older workers being less likely to use information and communication technologies (ICT).

Women in MENA have jobs more amenable to working from home. This is because women have jobs less intensive in physical tasks that are more likely to be location-specific and thereby cannot be done at home. Accordingly, they are more likely to use ICT at work than men. But these patterns across genders should be interpreted with caution, since our results do not consider other important factors driving gender differences during the pandemic.

First, the probability of working in a sector considered ‘essential’ may be different across genders. Jobs in construction, agriculture and transport tend to be dominated by mean, and also rank low in their amenability to working from home (see chart), but they have typically been considered ‘essential’ in several economies. That is, workers in those sectors can usually keep their jobs despite being unable to work from home.

Second, gender-biased social norms regarding the division of childcare or home schooling in the family may affect women’s jobs disproportionately. Even in the United States, a recent survey shows that while almost half of men say they do most of the home schooling, only 3% of women agree.
In addition to providing new stylised facts, our estimates can help shed light on why certain regions or types of workers have jobs less amenable to working from home, which is a key issue for the design of public policies.

For example, the policy response would be very different if the low amenability to working from home is driven by jobs being too physically intensive rather than by people not using ICT at work. If the former is true, policies to help workers find another occupation or to provide income-support might be more adequate.

In contrast, if the amenability to working from home is low because people do not use ICT at work to conduct interpersonal tasks, then policies that give firms incentives to use more ICT or to increase digital literacy among workers might be the way to go.

Finally, if people cannot work from home because they lack internet connectivity at home, the policy response would be to address the bottlenecks that keep people from connecting online.

The benefits of improving access to digital technologies in MENA cannot be emphasised more, both in normal times and during the pandemic. In fact, a recent study shows that the rapid rollout of mobile broadband in Jordan since 2010 had dramatic impacts on female labour force participation, and on the employment rates of skilled women. Moreover, higher internet access was also linked with a reduction in gender-biased social norms, early marriage and fertility.

But the adoption of new technologies does not happen overnight, especially when the baseline level is very low as in the MENA region – less than half of the workers in the three countries we analysed have internet access at home and only 13% use the internet in their jobs. Thereby, a broader response stimulating the economy and supporting those who cannot find a job is key.
Most read

How trade policy can reduce MENA’s cereal import vulnerability

Heavy dependence on imported cereals, combined with climate change, water scarcity and geopolitical uncertainty, continues to threaten food resilience across MENA. This column explains how an inclusive trade policy can play a key role in making the region’s food security less vulnerable to shocks.

Digitalisation, global value chains and regional integration in MENA & SSA

Participation in global value chains is vital for countries pursuing structural transformation and inclusive economic development. This column summarises new evidence on how much production processes have been globalised in Africa and the Middle East relative to other regions; whether this process has taken place with partners within or outside the region; and whether it has taken place more in manufacturing or services.

The risks of a two-speed AI economy in MENA

Much of the debate about artificial intelligence in the Middle East and North Africa focuses on how many jobs it will replace. As this column explains, the more important challenge is that the new technology is likely to create a two-speed labour market, where countries with the capacity to invest in digital infrastructure and skills move rapidly ahead while others struggle to keep pace. Unless governments combine credible national reforms with targeted regional cooperation, AI could widen, not reduce, the economic divides across MENA.

Financing Lebanon’s Reconstruction: A Compact for Finance, Governance, and Accountability

As Lebanon embarks on another round of reconstruction, the key question is not how much financing can be mobilised, but whether each commitment is linked to a verified need, involves a transparent procurement process, is linked to clearly defined executing and operating institutions, and is based on a liability that is in line with the state’s ability to repay. This column proposes an operational mechanism for establishing that connection: a Reconstruction Finance and Accountability Compact.

Sanctions and conflict: why corruption changes the equation

Why do sanctions produce such different political outcomes across the countries that have been targeted? This column reports research examining the role of pre-existing corruption in shaping the relationship between sanctions and subsequent conflict or political instability. The evidence indicates that trade sanctions are associated with higher conflict-related deaths where pre-existing corruption is high.

The weak bread chain: cereal supply risks in six MENA economies

The Middle East and North Africa is one of the most food-import-dependent regions of the world, particularly for staple cereals such as barley, maize and wheat, and particularly in six countries – Algeria, Egypt, Jordan, Lebanon, Morocco and Tunisia. As this column reports, diversifying import sources has become an essential strategy for strengthening food security and improving resilience to geopolitical and climate-related disruptions.

From mega-investment to mega-productivity: closing MENA’s conversion gap

Across the Middle East and North Africa, governments are investing heavily in infrastructure, technology, diversification and new industries. Yet capital accumulation alone does not guarantee productivity growth. As this column argues, the region’s deeper challenge is its ‘investment-to-productivity conversion gap’: ensuring that large-scale investment translates consistently into stronger firms, technological diffusion, skills and better jobs. A different metric of success is required: not how much capital is deployed, but how much productive capability that capital leaves behind.

Why energy efficiency still struggles to attract finance in Egypt

Egypt has reduced energy subsidies and gradually adjusted domestic energy prices toward cost-recovery levels, improving the economic case for energy efficiency investments – but financing has not kept pace. Drawing on structured interviews with banks, developers and public officials, this column traces why energy efficiency projects in the country still struggle to attract capital, and sets out how a ‘financing ladder’ used elsewhere – from revolving funds to risk guarantees to green bonds – could close the gap.