

Economic Research Forum (ERF)

Has international migration reduced internal migration in Egypt?

4146
Urbanisation is key for economic development, yet Egypt has been lagging behind most other North African countries in this respect in recent decades. This column reports that the country’s lack of urbanisation is partly explained by very low internal migration rates, which in turn seem to have been dampened by high rates of international migration by Egyptians.

In a nutshell

Egypt’s total population has doubled in the last 30 years – yet the share of the population living in urban areas has not changed.

Approximately 60% of Egypt’s population still live in rural areas; internal migration rates are very low relative to the global average.

International migration prospects are likely to have dampened internal migration in Egypt.

Egypt has experienced substantial population growth over the last few decades. The country’s population has doubled in 30 years and reached 100 million in 2019 (UNDP, 2019).

Yet the rate of urbanisation has hardly changed in Egypt over the past 50 years. Since 1970, the share of the population that is urban has remained around 43% (UNDP, 2018). Moreover, urbanisation in the rest of North Africa has substantially surpassed that in Egypt.

In 1950, Egypt was among the leading countries in North Africa in terms of urbanisation. In 2018, Egypt had the lowest urbanisation rate among other neighbouring North African countries, including Algeria, Libya, Morocco and Tunisia (David et al, 2019). The urbanisation rate in Egypt stands at 43%, while the rate in the other North African countries is close to or higher than 70%.

We explore the extent to which internal migration has been responsible for the slow urbanisation in Egypt. Furthermore, given the importance of international migration, we investigate the relationship between international migration and internal migration.

In David et al (2019), we examine the evolution of internal migration rates in Egypt by decade of migration, focusing on various types of mobility: mobility between regions, governorates, cities or towns (qism/markaz) and villages (shyakha). We show that internal migration rates have been very low in Egypt, and we also find suggestive evidence that internal migration rates have been declining over time, since the 1980s.

For example, the regional migration rate went down from 2.6% in the 1980s to 1.7% in 2010s. Similarly, the internal migration rate between governorates decreased in the 2010s to reach 1.5% relative to 3% in the 1980s (Figure 1).
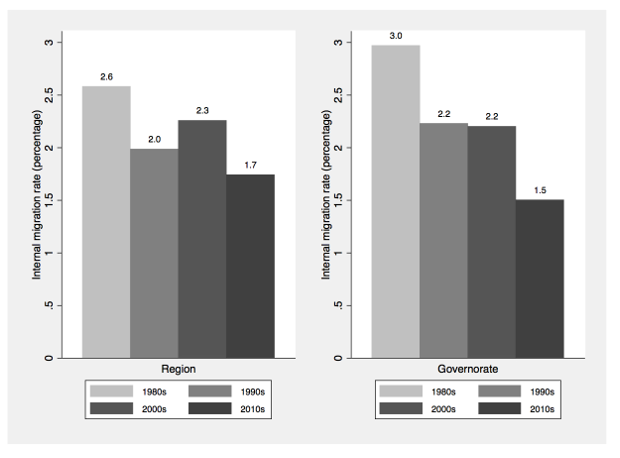
Figure 1: Internal migration rates (percentage) by decade of migration, mobility between regions and governorates

Notes. This figure features internal migration rates by decades of migration. This figure features mobility between regions (left panel) and mobility between governorates (right panel).

Moreover, we find that rural-urban migration has remained very low and that similarly, it has witnessed a decline over time. Migration rates from urban to rural areas have been almost equal to rural to urban migration rates over the past few decades. Taking into account urban to rural migration explains the very low and stable urbanisation rate in Egypt.

While internal migration has been very low, Egypt has been experiencing a steady flow of temporary international emigration, predominantly to other Arab countries and particularly to the Gulf States. We find that in 2018, almost 2% of individuals between 15 and 59 years old were international migrants and 7% were return migrants.

Furthermore, when we consider the rates of international and return migration experiences at the household level, we find that in 2018, 11% of Egyptian households either have or had an international migrant. We also find that these rates were even higher in 2012, which is likely to be a reflection of the impact of more restrictive immigration policies in destination countries.

Given the low rate of internal migration relative to international migration in the broad picture of mobility in Egypt, we explore the relationship between internal and international migration. More specifically, we examine whether international and internal migration substitute or complement each other.

Indeed, we find that in both 2012 and 2018, less than 1% of individuals aged between 15 and 59 years old were both internal and return migrants. These figures suggest that most individuals who engage in either internal or international migration do so solely without engaging in both types of mobility. It is also worth noting that we find that in 2018, the share of individuals who migrated overseas and returned is higher than the share of individuals who moved internally.

Urbanisation is key for economic development. While most North African countries have made major advances in this respect in recent decades, Egypt is still lagging behind and urbanisation rates have been stagnant since 1970. We find evidence that the lack of urbanisation in Egypt is partly explained by very low internal migration rates and that international migration prospects are likely to have dampened internal migration in Egypt.

Further reading

David, Anda, Nelly El-Mallakh and Jackline Wahba (2019) ‘Internal versus International Migration: Together or Far Apart’, ERF Working Paper (forthcoming).

UNDP, United Nations (2019) World Population Prospects: The 2019 Revision, Department of Economic and Social Affairs, Population Division.

UNDP, United Nations (2018) World Urbanization Prospects: The 2018 Revision, Department of Economic and Social Affairs, Population Division.


Most read

Beyond job creation: how can Egypt’s gender gap in work be closed?

More than 2 million jobs are needed each year to absorb new entrants into Egypt’s labour market and raise the country’s employment rate. The job challenge is even more acute for women, whose labour force participation remains low despite recent gains in education. This column reports on the second Development Dialogue, an ERF–World Bank Group joint initiative, which brought together students, scholars, policy-makers and private sector leaders at the American University in Cairo to consider how the country’s gender gap in work can be closed.

Digitalisation, global value chains and regional integration in MENA & SSA

Participation in global value chains is vital for countries pursuing structural transformation and inclusive economic development. This column summarises new evidence on how much production processes have been globalised in Africa and the Middle East relative to other regions; whether this process has taken place with partners within or outside the region; and whether it has taken place more in manufacturing or services.

How trade policy can reduce MENA’s cereal import vulnerability

Heavy dependence on imported cereals, combined with climate change, water scarcity and geopolitical uncertainty, continues to threaten food resilience across MENA. This column explains how an inclusive trade policy can play a key role in making the region’s food security less vulnerable to shocks.

The political economy of algorithms in the Middle East

The Middle East is entering a new political-economic era – one in which algorithms, data and artificial intelligence may become as strategically important as oil once was. Across the region, governments are investing heavily in digital infrastructure, smart governance and AI-driven economic transformation. This column outlines how AI and algorithmic governance are reshaping power, inequality and state capacity in the region.

The risks of a two-speed AI economy in MENA

Much of the debate about artificial intelligence in the Middle East and North Africa focuses on how many jobs it will replace. As this column explains, the more important challenge is that the new technology is likely to create a two-speed labour market, where countries with the capacity to invest in digital infrastructure and skills move rapidly ahead while others struggle to keep pace. Unless governments combine credible national reforms with targeted regional cooperation, AI could widen, not reduce, the economic divides across MENA.

From mega-investment to mega-productivity: closing MENA’s conversion gap

Across the Middle East and North Africa, governments are investing heavily in infrastructure, technology, diversification and new industries. Yet capital accumulation alone does not guarantee productivity growth. As this column argues, the region’s deeper challenge is its ‘investment-to-productivity conversion gap’: ensuring that large-scale investment translates consistently into stronger firms, technological diffusion, skills and better jobs. A different metric of success is required: not how much capital is deployed, but how much productive capability that capital leaves behind.

Sanctions and conflict: why corruption changes the equation

Why do sanctions produce such different political outcomes across the countries that have been targeted? This column reports research examining the role of pre-existing corruption in shaping the relationship between sanctions and subsequent conflict or political instability. The evidence indicates that trade sanctions are associated with higher conflict-related deaths where pre-existing corruption is high.

Why energy efficiency still struggles to attract finance in Egypt

Egypt has reduced energy subsidies and gradually adjusted domestic energy prices toward cost-recovery levels, improving the economic case for energy efficiency investments – but financing has not kept pace. Drawing on structured interviews with banks, developers and public officials, this column traces why energy efficiency projects in the country still struggle to attract capital, and sets out how a ‘financing ladder’ used elsewhere – from revolving funds to risk guarantees to green bonds – could close the gap.

The weak bread chain: cereal supply risks in six MENA economies

The Middle East and North Africa is one of the most food-import-dependent regions of the world, particularly for staple cereals such as barley, maize and wheat, and particularly in six countries – Algeria, Egypt, Jordan, Lebanon, Morocco and Tunisia. As this column reports, diversifying import sources has become an essential strategy for strengthening food security and improving resilience to geopolitical and climate-related disruptions.