Economic Research Forum (ERF)

Palestinians working in Israel: the impact on West Bank food security

1631
Employment of Palestinians in Israel is one of the special features of the labour markets in the West Bank. But this employment is volatile as closures and regulations administered by the Israeli authorities control Palestinians’ access. This column reports research simulating different levels of the employment of Palestinian labour in Israel and assesses their implications for food security in the West Bank.

In a nutshell

A return of the level of Palestinian employment in Israel to its pre-intifada level improves households’ incomes in the West Bank and their access to food.

To match the higher demand associated with more employment of Palestinian labour in Israel, both imports and the supply of domestic output to the domestic market increase: hence the availability of food in the West Bank improves.

From a policy perspective, the Palestinian National Authority may seek with the Israeli authorities an increased Palestinian employment in Israel to improve household welfare and food security in the West Bank.

The conflict between Israel and Palestine attracts substantial media attention for its violence, historical background and political developments. But the economy-wide implications of different policies in Palestine, especially those related to labour mobility, are understudied.

Our research examines various policy options focusing on the labour market with the aim of achieving faster economic growth and improved food security in the West Bank.

We use a computable general equilibrium model calibrated to a unique database for the West Bank to simulate a return of Palestinian employment in Israel to its pre-intifada level of 1999. This corresponds to an increase in the number of Palestinian workers in Israel by 36% compared with its level in the base year of 2011.

We assess the effects on the whole economy and the implications for food availability and consumption. The results show a GDP increase by 3.6% in real terms and an improvement in the welfare of West Bank’s households by 5.5% on average.

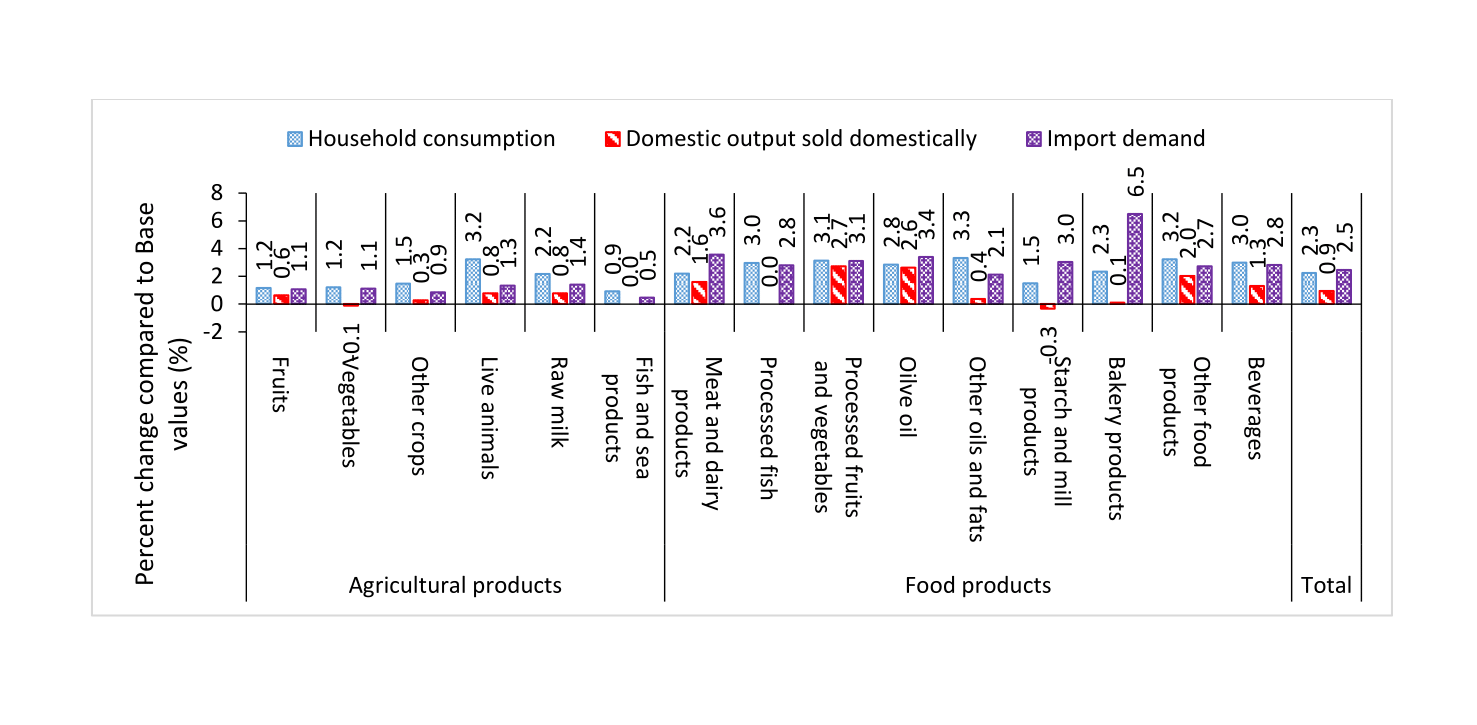
Household consumption of agricultural and food products increases on average by 2.3%. The availability of agricultural and food products in the domestic market increases as import demand rises on average by 2.5% and domestic output sold domestically by 0.9% (see Figure 1).

By contrast, reducing Palestinian employment in Israel by 36% leads to a contraction of the West Bank economy and welfare losses for Palestinian households.

Consumption of agricultural and food products decreases on average by 2.2%. The availability of food and agricultural products drops, as import demand declines by 2.3% and domestic output sold domestically decreases by 0.8%.

In light of these results and the limited development options in the Palestinian territories, the Palestinian National Authority (PNA) may seek increased employment of Palestinian workers in Israel, as a ‘second-best’ policy, in order to improve household welfare and food security.

Increased employment of Palestinian labour in Israel and the associated large inflow of additional labour income from Israel have ‘Dutch disease’ effects, causing the competitiveness of the Palestinian export sector to decline, including agricultural and food exports.

Therefore, the PNA may consider introducing a tax on Palestinian workers employed in Israel. This may raise revenue that can be used to provide incentives for local producers, including farmers, to adopt new production technologies and restore their competitiveness on international markets.

Further reading

Johanes Agbahey, Khalid Siddig, Harald Grethe and Scott McDonald (2018) ‘Labour Exports from Palestine to Israel: A Boon or Bane for the West Bank Economy’, 30th International Conference of Agricultural Economists (ICAE), Vancouver, Canada, July-August 2018 (full paper).

Figure 1:
Changes in food availability when the employment of Palestinians working in Israel returns to its pre-intifada level
Most read

Financing Lebanon’s Reconstruction: A Compact for Finance, Governance, and Accountability

As Lebanon embarks on another round of reconstruction, the key question is not how much financing can be mobilised, but whether each commitment is linked to a verified need, involves a transparent procurement process, is linked to clearly defined executing and operating institutions, and is based on a liability that is in line with the state’s ability to repay. This column proposes an operational mechanism for establishing that connection: a Reconstruction Finance and Accountability Compact.

Sanctions and conflict: why corruption changes the equation

Why do sanctions produce such different political outcomes across the countries that have been targeted? This column reports research examining the role of pre-existing corruption in shaping the relationship between sanctions and subsequent conflict or political instability. The evidence indicates that trade sanctions are associated with higher conflict-related deaths where pre-existing corruption is high.

The weak bread chain: cereal supply risks in six MENA economies

The Middle East and North Africa is one of the most food-import-dependent regions of the world, particularly for staple cereals such as barley, maize and wheat, and particularly in six countries – Algeria, Egypt, Jordan, Lebanon, Morocco and Tunisia. As this column reports, diversifying import sources has become an essential strategy for strengthening food security and improving resilience to geopolitical and climate-related disruptions.

The risks of a two-speed AI economy in MENA

Much of the debate about artificial intelligence in the Middle East and North Africa focuses on how many jobs it will replace. As this column explains, the more important challenge is that the new technology is likely to create a two-speed labour market, where countries with the capacity to invest in digital infrastructure and skills move rapidly ahead while others struggle to keep pace. Unless governments combine credible national reforms with targeted regional cooperation, AI could widen, not reduce, the economic divides across MENA.

Why energy efficiency still struggles to attract finance in Egypt

Egypt has reduced energy subsidies and gradually adjusted domestic energy prices toward cost-recovery levels, improving the economic case for energy efficiency investments – but financing has not kept pace. Drawing on structured interviews with banks, developers and public officials, this column traces why energy efficiency projects in the country still struggle to attract capital, and sets out how a ‘financing ladder’ used elsewhere – from revolving funds to risk guarantees to green bonds – could close the gap.

From mega-investment to mega-productivity: closing MENA’s conversion gap

Across the Middle East and North Africa, governments are investing heavily in infrastructure, technology, diversification and new industries. Yet capital accumulation alone does not guarantee productivity growth. As this column argues, the region’s deeper challenge is its ‘investment-to-productivity conversion gap’: ensuring that large-scale investment translates consistently into stronger firms, technological diffusion, skills and better jobs. A different metric of success is required: not how much capital is deployed, but how much productive capability that capital leaves behind.

Iran is still selling oil. But can it replace tomorrow’s barrels?

Iran’s oil exports have not disappeared, but continued sales may hide a deeper vulnerability. Arash Irani argues that selling barrels already in the logistics system is not the same as generating new export flows, and proposes five indicators to help policymakers judge whether trade under disruption is sustainable or merely running down its stocks.

The political economy of turning AI adoption into firm productivity in MENA

Generative AI can make individual tasks faster without making firms more productive. This column argues that across the Middle East and North Africa, turning AI adoption into better performance depends on organisational capabilities and on agreements within firms over authority, workloads and rewards. Public support can help by financing those capabilities through transparent selection, milestone-based assistance and independent evaluation.

Uneven growth, shallow integration: the case for deeper MENA cooperation

The war-related shock of 2026 has pushed economies across the Middle East and North Africa onto sharply different growth paths. This column argues that these short-term differences say little about long-term income convergence, but that they expose a more durable weakness: shallow regional integration. It proposes three measures to make MENA cooperation deliver tangible economic benefits.

Losing comparative advantage: the erosion of Lebanon’s export base

Lebanon's competitive exports were worth about $3 billion in both 2018 and 2022, but the steady total hides a narrower base. Mohamad Abou Haidar and Ali Fakih show that more than a third of that value rests on precious metals and scrap. They argue that export policy should start by establishing how much of Lebanon's export value reflects domestic production, and should support products on the basis of evidence on value added and viability rather than on trade rankings alone.