In a nutshell
To address the coming surge in Egypt’s labour supply and avoid an increase in unemployment rates, the government must maintain a fairly rapid rate of economic growth; what is likely to be needed is a rate in excess of 7% per year.
Policy-makers should also strive to transform the growth pattern into one that generates higher quality jobs that are suited for educated workers, especially educated young women; growth based on infrastructure and real estate generates low-quality jobs.
Rapid expansion of the ICT sector, in particular, and the digital economy, in general, can create the type of employment that the large wave of increasingly educated workers soon to enter the Egyptian labour market would aspire to.
Unemployment in Egypt has always had a substantial structural component linked to demographics, as it is highly concentrated among young, educated new entrants to the labour market. When the growth of the youth population slows, as was the case in the past decade and a half, there is reduced demographic pressure on the labour market and unemployment tends to decline. As the growth of this group resumes from 2025 to 2035, labour supply pressures will increase, and there will be substantial upward pressure on the unemployment rate during this period (Assaad, 2022).
The echo generation comprises the sons and daughters of the ‘youth bulge’ generation, which resulted from rapid declines in infant and child mortality rates in the early to mid- 1980s when fertility rates were still relatively high. The youth bulge generation reached child-bearing age from the mid-2000s to the early 2010s, also coinciding with a period of increased fertility from 2008 to 2014, resulting in a substantial baby boom that lasted roughly from 2005 to 2015.
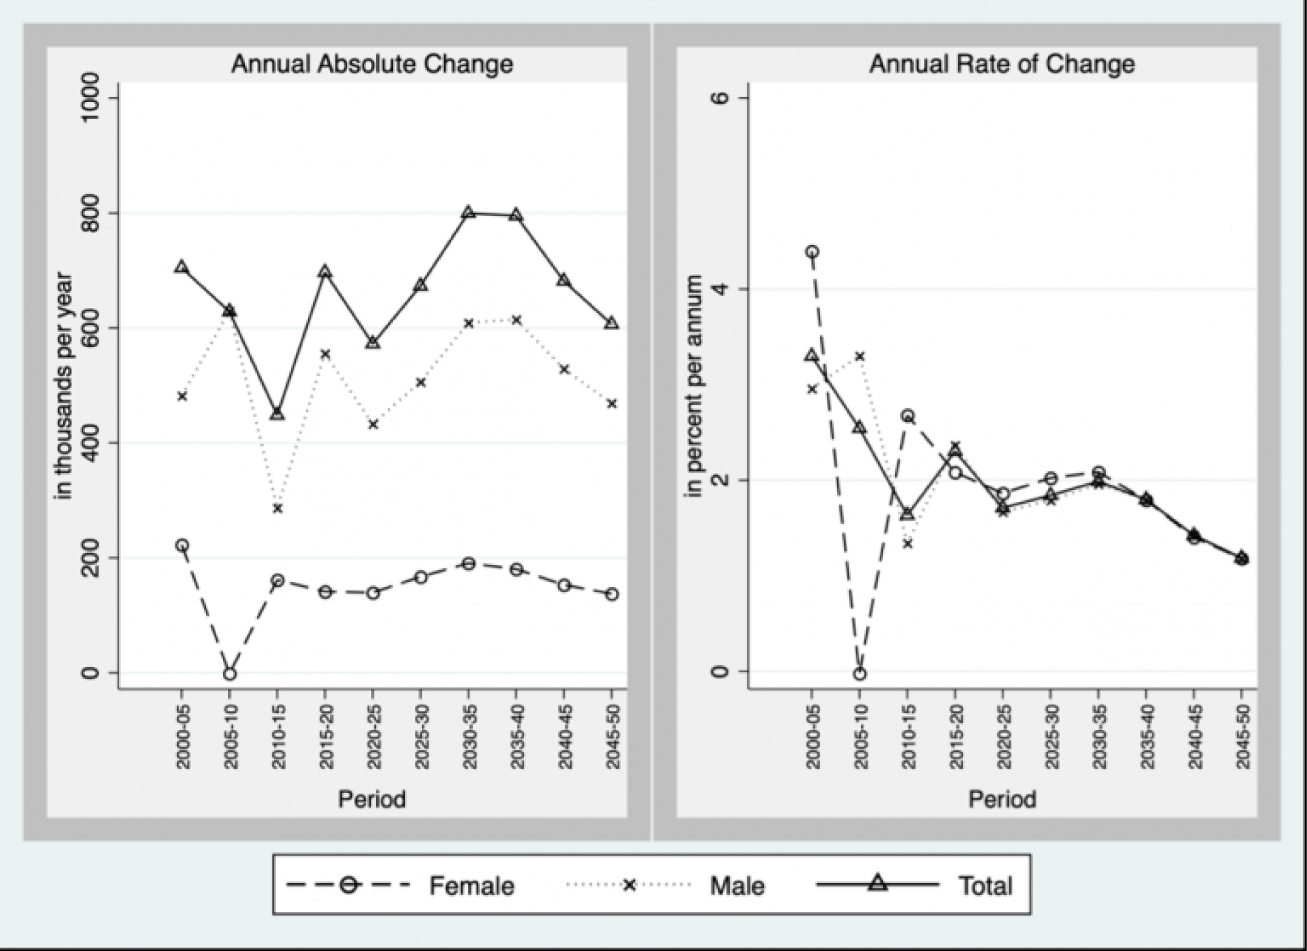
The echo generation, born during this interval, will be of age to start entering the labour market from 2025 to 2035, which will substantially increase the number of new labour market entrants and the rate of growth of the labour force. As shown in Figure 1, the annual increment to the labour force will increase from under 600,000 a year in 2020-25 to 800,000 a year from 2025 to 2035. This will also be a period of rising growth rates after the recent dramatic slowdowns in labour force growth.
These dramatic increases in new labour market entrants will translate into substantial labour supply pressures in the Egyptian labour market. Given the gradual rise in educational attainment in Egypt in recent years, it is projected that more than two-thirds of labour market entrants in 2030 will have achieved at least secondary education. It is well established in Egypt that unemployment rates are usually highest for those with secondary education and above, resulting in further upward pressure on unemployment (Krafft et al, 2022).
Women’s participation in the labour market has been falling in recent years in Egypt. In fact, the labour force participation rate of women has declined from 23% in 2012 to 21% in 2018 (Krafft et al, 2022). This decline has been attributed to a degree of discouragement by educated young women, as public sector employment opportunities – their preferred form of employment – have contracted. If this declining trend stabilises or reverses, there will be further labour supply pressures in the upcoming decade.
What can the Egyptian government do?
What can the Egyptian government do to address this coming surge in labour supply and avoid an increase in unemployment rates?
First, it must maintain a fairly rapid rate of economic growth. Assaad (2022) estimates that growth rates in excess of 7% per year are necessary to create sufficient employment to maintain stable unemployment rates.
Second, it must strive to transform the growth pattern into one that generates higher quality jobs that are suited for educated workers, especially educated young women. Egypt has relied excessively in recent years on the growth of infrastructure and real estate as a primary engine of growth (Amer et al, 2021). This growth pattern generates low-quality jobs that are particularly unattractive to young women.
The second stage of Egypt’s National Programme for Economic and Social Reforms aims to increase the relative weight of three economic sectors, namely the manufacturing sector, the agricultural sector and the information and communications technology (ICT) sector (Ministry of Planning and Economic Development, 2021).
The ICT sector employment and increased demand
If successful, these structural reforms can go a long way in creating the sort of employment that meets the expectations of educated new entrants. The ICT sector, in particular, has seen large increases in labour demand in recent years and has been particularly hospitable to women.
According to Selwaness et al (2023), although the share of ICT jobs in total employment has been small (1.8% in 2021), private sector employment in such jobs grew rapidly, at a rate of 5.5% per annum, well above the 2.1% per annum growth rate of non-ICT jobs in the 2009-21 period. While women’s employment in the private sector in non-ICT jobs has been declining at a rate of 1.4% per annum, it has been growing at the meteoric rate of 10% per annum in ICT jobs.
Moreover, the educational composition of ICT jobs is much more heavily weighted toward educated workers, with up to 63% having tertiary education or above, and 28% having secondary or post- secondary education (Selwaness et al, 2023). This compares with 15% and 35%, respectively, in non-ICT jobs.
This suggests that the rapid expansion of the ICT sector, in particular, and the digital economy, in general, can create the type of employment that the large wave of increasingly educated workers soon to enter the Egyptian labour market would aspire to. Despite its currently small size, accelerating employment creation in this sector can help to avert or at least to mitigate the significant increases in unemployment that are the likely result of the echo generation reaching labour market in the decade starting in 2025.
Further reading
Amer, Mona, Irène Selwaness and Chahir Zaki (2021) ‘Labour Market Vulnerability and Patterns of Economic Growth: The Case of Egypt’, in Regional Report on Jobs and Growth in North Africa 2020, International Labour Organization.
Assaad, Ragui (2022) ‘Beware of the Echo: The Evolution of Egypt’s Population and Labor Force from 2000 to 2050’, Middle East Development Journal 0(0): 1-31.
Krafft, Caroline, Ragui Assaad and Caitlyn Keo (2022) ‘The Evolution of Labor Supply in Egypt, 1988-2018: A Gendered Analysis’, in The Egyptian Labor Market: A Focus on Gender and Economic Vulnerability, Oxford University Press.
Ministry of Planning and Economic Development (2021) ‘The National Programme for Structural Reforms: The Second Stage of the National Programme for Economic and Social Reform’.
Selwaness, Irène, Ragui Assaad and Mona El Sayed (2023) ‘The Promise of Information and Communication Technology (ICT) Jobs in Egypt’, GIZ, Egypt.
This column was originally published at Open Access Government. See the original article.
